The Strata Property Act requires the strata corporation to provide insurance as follows.
Property insurance required for strata corporation
149 (1) The strata corporation must obtain and maintain property
insurance on (a) common property, (b) common assets, (c) buildings
shown on the strata plan, and (d) fixtures built or installed on a
strata lot, if the fixtures are built or installed by the owner
developer as part of the original construction on the strata lot.
(4)
The property insurance must (a) be on the basis of full replacement
value, and (b) insure against major perils, as set out in the
regulations, and any other perils specified in the bylaws.
Liability insurance required for strata corporation
150 (1) The strata corporation must obtain and maintain liability insurance to insure the strata corporation against liability for property damage and bodily injury.
(2) The insurance must be of at least the amount required in the regulations.
Errors and omissions insurance
151
The strata corporation may obtain and maintain errors and omissions
insurance for council members against their liability and expenses for
errors and omissions made in the exercise of their powers and
performance of their duties as council members.
Named insureds
155
Despite the terms of the insurance policy, named insureds in a strata
corporation’s insurance policy include (a) the strata corporation, (b)
the owners and tenants from time to time of the strata lots shown on the
strata plan, and (c) the persons who normally occupy the strata lots.
Application of insurance money
157
Insurance money received under section 156 with respect to damaged
property must be used to repair or replace the damaged property without
delay unless the strata corporation decides not to make the repair or
replacement under section 159.
Insurance deductible
158
(1) Subject to the regulations, the payment of an insurance deductible
in respect of a claim on the strata corporation’s insurance is a common
expense to be contributed to by means of strata fees calculated in
accordance with section 99 (2) or 100 (1).
(2)
Subsection (1) does not limit the capacity of the strata corporation to
sue an owner in order to recover the deductible portion of an insurance
claim if the owner is responsible for the loss or damage that gave rise
to the claim.(3)
Despite any other section of this Act or the regulations, strata
corporation approval is not required for a special levy or for an
expenditure from the contingency reserve fund to cover an insurance
deductible required to be paid by the strata corporation to repair or
replace damaged property, unless the strata corporation has decided not
to repair or replace under section 159.
Decision not to repair or replace
159 (1) The strata corporation may, by a resolution passed by a 3/4 vote at an annual or special general meeting held no later than 60 days after the receipt of the money referred to in section 156, decide not to repair or replace the damaged property.
(2)
Subject to section 160, if the strata corporation decides not to repair
or replace the damaged property, the insurance trustee or the strata
corporation that receives the payment under subsection (1) of this
section holds the money and any interest on the money in trust for each
person who has an interest in the money, including the holder of a
registered charge, and
(a) must distribute the money according to each person’s interest, or
(b)
if an application is made under section 160, must distribute the money
in accordance with the order made under that section.
*****************
https://www.investopedia.com/terms/i/insurance.asp
insurance is a contract, represented by a policy; pools risks to make payments more affordable; used to hedge against risk of losses that may result from damage or liability for injury (eg."all in it together" strata policy & deductible, replacement value -db)
http://www.bclaws.ca/civix/document/id/complete/statreg/98043_09
the SPA governs s149 water damage repair, s155 named insureds include owners despite terms of strata's policy, s156 insurance proceeds are paid to strata in TRUST until paid under s157, strata pays s158 deductible, or sues if it can prove owner is responsible (strata insurance seems like a trust -db)
https://www.valuepenguin.com/choosing-homeowners-insurance-deductible
a deductible is the amount of money a policyholder must pay out-of-pocket toward damages or a loss before their insurance company will pay for a claim (s.158 strata pays deductible per s.99 strata fees, otherwise strata must sue to prove an owner is responsible to pay -db)
*****************
This whole article is worth posting, with added emphasis (and comment)
Choosing The Right
Homeowners Insurance Deductible
Choosing the right
deductible is vital to getting the most out of your homeowners insurance policy. Every policy has
a deductible so every person buying homeowners insurance will have to make this
decision. The guide below will help you understand your deductible and
calculate what yours should be.
Homeowners
Insurance Deductibles
A deductible is the
amount of money a policyholder must pay out-of-pocket toward damages or a loss
before their insurance company will pay for a claim.(NOTE: the STRATA corporation is the POLICY HOLDER, and the deductible amount is a S.158 COMMON EXPENSE to be paid by s.99 strata fees) You do not actually pay
your deductible to your insurance company like you would a premium or bill. If
you file a claim and it is covered, the deductible is subtracted from the
amount claimed. For example, say you have a $500 deductible and you file a
claim for $10,000. Your insurance company would pay you $9,500 for that claim.
There are
generally two types of deductibles: a dollar-amount
and a percentage based. The difference between them is how your deductible is
calculated, and there are a couple of nuances depending on how much your home
is valued at. Once calculated, the amount a homeowner pays if they file a claim
is fixed for the length of that policy.
How to Choose a
Deductible for Your Policy
Your home insurance
deductible should be as high as you can reasonably afford because the higher
your deductible, the lower the cost of your premium. Raising your deductible
can reduce the cost of your homeowners insurance premium as much as 20%, but
that does not mean you should raise your deductible as high as possible.
When choosing a
deductible, what you’re really doing is balancing the short-term cost you can
afford (your deductible) and the long-term cost of a policy (your premiums). (NOTE: balancing risks and costs is fine, but OFFLOADING them onto an owner WITHOUT SUING TO PROVE RESPONSIBILITY is unlawful. Due process is explicitly required under the SPA.) The more you can afford in the short-term, the more you’ll save in the
long-term because your premiums will be lower. Insurance companies design the
products this way to encourage homeowners to assume more of their own risk and
to reduce administrative costs for small claims. For example, the premiums
would be higher for a policy that has a $500 deductible versus a $1,000
deductible because the policyholder elected to assume greater financial risk.
They would have to pay $1,000 toward a claim instead of $500 if they had to
file one.
There are other
reasons it makes sense to raise your deductible. Every insurance company is
different but typically if you file a claim for any amount, the cost of your
premium will increase because you've essentially become a riskier and costlier
homeowner to insure. And the more claims you file, the higher your premium will
be. For that reason, there are circumstances in which even if you have a low
deductible, it might not be in your best financial interest to file a claim.
For example, say
you have a $500 home insurance deductible. If wind destroys a small part of
your roof and causes $1,000 in damages, you probably shouldn’t file a claim if you
can afford to pay for the damages out-of-pocket. Yes, you could have your
insurance company cover the $500 after your deductible but the cost of your
premium might increase. That increase might be small or large, depending on the
amount claimed and especially the number of claims you’ve made. If you file
multiple claims, the cost of your premiums could go up as much as 25% or more
and you never know what what the future holds. After the small wind damage,
hail could destroy your roof entirely and a tornado could damage your home a
month later. All of a sudden you haven’t made it through the spring of one
calendar year and you’ve already filed three claims. So if you’re in a
financial position to consider paying for small damages or losses out-of-pocket,
then you should increase your deductible and lower your monthly premiums. (NOTE: so if the STRATA CORPORATION POLICY HOLDER is in a position to pay small amounts it can increase ITS OWN deductible, but owners should not be PAYING PREMIUMS TWICE to cover the DEDUCTIBLE on major perils with FULL replacement coverage mandated by statute) If
you remain claim-free for usually three years, companies can lower your premium
rate.
Keep in mind that
many insurance companies offer a one-time discount to customers who have never
filed a home insurance claim. The discount might lower the cost of a standard
policy anywhere from 5 to 20% depending on the company. If you file a claim and
negate that discount, the cost of your premium will increase.
You should also
keep in mind your emergency or available funds with an eye toward paying your
deductible. While raising it can drop your rates, it should not do so at the
cost of financial stress. (NOTE: increasing the amount of the deductible does not reduce the strata's STATUTORY OBLIGATION TO PROVIDE REPLACEMENT VALUE REPAIR COVERAGE FOR MAJOR PERILS) Everyone should have a liquid emergency fund in the
event of unpredictable circumstances. A homeowners insurance deductible might
be one of those so consider what you you have saved for an emergency when
choosing your deductible. (NOTE: increasing the amount of the deductible means considering the strata's CONTINGENCY RESERVE FUND, not arbitrarily OFFLOADING corresponding costs onto some poor victimized owner) At the same time, it’s not a good idea for your
deductible to entirely wipe out the savings you’ve set aside for an emergency.
You might need additional emergency funds at the time you have to file a
homeowners insurance claim. For example, say a fire or tornado destroys half of
your home and it is uninhabitable. Most homeowners policies also offer
additional living expense coverage to take care of hotels bills, restaurant
meals and other expenses. But what if you reach your limits for those expenses
or need money for another emergency? If your deductible consumes your entire
emergency savings, you might not have the money to cover those expenses.
How Your
Deductibles Impact Your Home Insurance Rates
Below are some
examples of the impact a deductible will have on a premium. We calculated the
changes to a premium for a sample policy from State Farm assuming several
different deductible scenarios, which is the company with the largest share of
the homeowners insurance market. Our example homeowner is insuring his dwelling
for $200,000, personal content for $150,000, and general liability of $100,000.
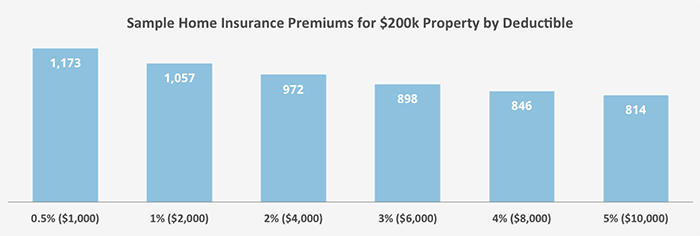
You can see that raising your deductible has a substantial impact on the
cost of your annual premium. (NOTE: I don't know what's wrong with this picture. We are paying so much more than anything shown in the chart that there is no comparison. In 2014 we paid about $675 of our strata fees for insurance premiums, with a $15,000 DEDUCTIBLE for water damage, when Unit 409's tax assessed BUILDING VALUE was $104,000. NW2671's December 31, 2017 balance sheet shows $16,724.84 in prepaid insurance, which the policy shows is to May 1, 2018. The strata's Income and Expense Comparative Statement shows the budget for insurance on 17 buildings was $58,714 for 2016 and $56,000 for 2017. This reduction reflects the reduced value of steadily DEPRECIATING buildings, For example, the premium for a sample policy
covering the replacement cost of a $200,000 home with a 0.5% (effectively a
$1,000 deductible) would be $1,173. The exact same coverage with a 1% / $2,000
deductible for our profiled homeowner would have an annual premium of $1,057
and a deductible of 5% on the house (which would equate to $10,000) would lower
the premium all the way to $814. Based on our policyholder, doubling your deductible
from 0.5% to 1% (that's from $1,000 - $2,000) could drop your annual homeowners
insurance premium down by 10%. Each incremental 1% point increase thereafter in
deductible reduces your rates about 4 - 8%. For this homeowner, increasing
their deductible sixfold (from a 0.5% / $1,000 to 3% / $6,000) resulted in a
23% lower premium.
*****************
"Strata Corporation Deductibles in Practice"
In Strata Corp. VR 2673 v. Comissiona, 2000 BCSC 1240, the
court held that the right to sue is determined by the strata corporation bylaws...
Churning out continual strata strife in an inherent conflict of interest, lawyers are in my opinion instrumental in developing
strata industry standards that conflict with the SPA. Introducing, for example, the notion that the strata can "download”
the deductible to the unit owner contrary to s.158(1) by means of a bylaw that would avoid
due process and the requisite burden of proof to effectively defeat
the SPA, as well as oust the jurisdiction of the court contrary to s.158(2) and the principle of innocent until proven guilty.
In Mari v. OSP LMS 2835, 2007 BCSC 740, the BC Supreme Court judicially defined responsibility as distinguished from negligence. The court held that when the
strata proved that the owner of the unit from which water escaped was responsible for the damage, the strata could then recover its deductible from the owner even if the owner was not negligent...
From my perspective there are 2 ways of looking at insurance deductibles.
The SPA way treats major perils named in the policy as insured for full
replacement value in all cases, with the deductible amount a common expense paid by s.99 strata fees. Filing a Proof of Loss by the strata or owner under s.155 for evaluation
by the strata corporation's insurance adjuster and suing to prove an owner is responsible may be discretionary, but responsibility for replacement value repairs is not.
The
other way is to treat the deductible portion as uninsured. This
approach contradicts the SPA's mandatory requirement to provide "full
replacement value insurance against major perils" as set out in the
regulations, and any other perils specified in the bylaws. It encourages excessively high deductible amounts, induces strata
corporations not to file a proof of loss or commence a claim for recovery on the strata corporation's all risk property
policy within the requisite one year period following the
occurrence of the loss, leaves damaged property unrepaired contrary
to s.159, and attempts to offload insured risks onto individual owners contrary to the "all in it together" principle and the due process of law.
All of which is great for churning up legal disputes, but terrible for proper repairs and living in peace.
A 3-bedroom unit pays about 30% more of the strata corporation's insurance expense, indeed of all expenses, than a 2-bedroom unit.
Even though a strata
corporation’s insurance policy includes the owners as named insureds by law, and it seems like a waste of money for an owner to pay insurance premiums and
then not file a claim when there is damage, I found a rather interesting link explaining this issue at
http://completechoiceinsurance.com/7-times-you-shouldnt-file-an-insurance-claim.
I have summarized it as follows:
Filing a lot of claims is
almost certain to cost more in higher premiums over time than you will get from
claim settlements. Insurance companies report claims to industry wide
databases, so all of the companies can see your claim history. They set your
rates based not only on their assessment of your risk of having property
damage, but also for the risk to them that you will file a claim.
As a result, there are situations where you are better off
not filing a claim. For example, if the policy has a deductible of $1,000 and the
total damage is $900, then the insurance company won’t pay anything, and premiums could still go up. There is not much point in going through the hassle
of filing a claim, getting the damage appraised by an insurance adjuster, and
risking higher insurance premiums if it is likely that the damage is below the
deductible and you won’t get a payout anyway.
Even if your claim would be more than the deductible and you
would get a payout, if you have filed other recent claims, you are risking a
significant increase in rates by filing another one. The average person files a
claim about once every eight to 10 years, so if you file claims more frequently
than average, you could be setting yourself up for higher rates.
If a police report is filed, your insurance company will
likely find out about the incident whether you report it or not. One of the
benefits of getting your insurance company involved is to handle a potentially expensive
lawsuit. Even if your incident is minor, you may want to talk with your
insurance company if you get the feeling that the other party may pursue a
liability claim.
If the damage is a few thousand dollars or less, you might
still come out ahead by paying out of pocket rather than filing a claim. You
can avoid the risk of higher premiums for years and getting a record that can
follow you even if you look for insurance from a different provider.
Dog bites, water damage, and slip-and-fall claims are most
likely to trigger rate increases on your homeowners insurance, according to
Bankrate. Some insurance agents are obligated to report inquiries to the
insurance company, and a mere inquiry about your coverage can be used to raise
your rates due to the increased risk that you may file a claim. You can also
ask your agent if they are obligated to report the inquiry to the insurance
company before you start talking about a potential claim.
I can understand the strata having discretion to set the deductible, because no matter what the amount, it is a common expense. I can also understand the strata having discretion not to file an insurance claim for damage when it is unreasonable to
do so, because replacement value repairs are mandatory in any event.
I have a huge problem, however, when stratas set perversely high deductibles or purposefully avoid getting the damage appraised by an insurance
adjuster in order to defeat their statutory obligation to provide replacement value repairs, and instead leave strata lots with unrepaired
damage, especially when the strata or neighbours are responsible for that damage.
Our strata paid about
$25,000 for replacement value repairs for 2003 water damage from a broken toilet that was self contained within a single lower unit and the responsibility of the owners themselves.
Damage confined to one unit is by necessity less extensive than the damage a few days earlier to two units, when water escaping from a broken toilet in the upper level Unit 510 flooded both the source unit and our Unit 409 below when nobody was home in either unit to turn off the water.
The owner responsible for the toilet tank in Unit 510 was in charge of negotiating insurance for the strata at the time. The deductible was $1,000 in the notice given for the AGM
held within 2 months of the December 31, 2002 fiscal year end and
$5,000 in the notice given for the AGM held within 2 months of the
December 31, 2003 fiscal year end. I could not obtain a signed and dated copy of a policy actually in force at the time of loss.
In any case, the mandatory insurance required for major perils specifically includes full replacement value repairs for water damage, and as of 2018, the continuously incomplete repairs to Unit 409 are anything but full replacement value:
The strata lulled me into believing that the repairs to 409 would be completed and did not give me access to the insurance policy or advise me of my right to make a claim on the policy. It further prevented me from making a claim by starting to make repairs, which it then delayed until the time for a claim expired, leaving them incomplete.
The required vote for leaving damage unrepaired was not obtained since insurance
money was not received because an unidentified member of the strata
management team decided not to make the claim or complete the repairs.
I made extraordinary efforts to do everything in my power to obtain the required repairs and don't know whether to blame Garth Cambrey of Stratawest, Gloria Henderson of Unit 510, Sunridge Estates strata councils, or the whole combination for leaving 409 with all this unrepaired water damage. Regardless of blame, I think it's unlawful.
When
properties like units 409 and 510 are insured for a named peril like
water damage, changing the strata's deductible from $1,000 to $15,000 does
not prohibit making the claim or deprive owners of full
replacement value repairs.
Subsection
(2) does not make an owner responsible for the deductible. Strata
bylaws cannot either. Only a court can do that. The SPA requires the
strata to sue the owner and meet the burden of proof; it is NOT the
other way around.
I am asking the strata to complete repairs of 409 - or get the required 3/4 vote!!
It
is significantly unfair for the strata to provide full replacement value repairs to Unit 227 for damage they themselves were responsible for and deny 409 repairs for damage caused by another, and it is unlawful for the strata to fail to repair 409 by arbitrary delays,
misrepresentations, and denials.
I want the strata to complete the repairs or pay us the $25,000 with compound interest - or I would like 3/4 of the owners to look at Unit 409 with Eleanor Pedersen and explain to me over a cup of tea what she did to deserve repairs and what I did to become so victimized. I would apply to the Supreme Court for an order if that was appropriate, except that it is not, as I could never present evidence effectively, represent myself properly, or afford to get a lawyer to obtain the required order, all of which is NO SECRET!
When
it came to members of the strata management team preemptively cutting down trees around
Unit 409 contrary to s.71, poisoning me with toxic fumes, and torturing me with defamation, oppression, and harassment, no claim was made for vandalism to common property or personal injury to me.
No claim was made for errors and omissions either.
Labels: Strata Insurance, Strata Lawyer


